Your Portfolio Has A New Job: Retirement Income
Retirement income and tax planning for professionals and couples 5–10 years from retirement.
Fee-only fiduciary adviceSouth Orange County and nationwide virtually
You’ve spent decades building your savings. Now the decisions change.
The Sentient System™ brings those decisions together into one coordinated retirement strategy.
Who This Planning Is Designed For
This is typically a good fit if you:
- Are within 5-10 years of retirement
- Typically $500K or more invested for ongoing planning
- Project planning has no minimum
- Want clarity on how to turn your savings into income
- Care about reducing taxes, not just this year, but over time
- Prefer a thoughtful, long-term approach over quick answers
Two Ways to Work Together
You choose between them during the proposal and agreement step, before discovery begins.
Ongoing planning and investment management
A continuing relationship coordinating retirement income, taxes, and investments.
My typical minimum is approximately $500,000 in investable assets.
Project-based planning
A defined engagement with written findings and recommendations.
No asset minimum.
See What Your Retirement Paycheck Could Look Like
Start with a Fit Call. No spreadsheets to prepare and no need to have everything figured out.
When Building Stops, a Different Plan Begins
Once retirement is within reach, financial planning stops being about accumulation and starts being about turning what you’ve built into income you can actually live on.
The focus shifts to:
Building a retirement paycheck designed to last 25–30 years
Sequencing withdrawals to keep your lifetime tax bill as low as possible
Aligning your portfolio to fund your life, not just grow a number
Adapting as tax laws, markets, and your life change
Here’s how I structure that transition.
Five Steps. One Direction.
Step 1
Complimentary Fit Call
A short conversation with me about your goals and questions, and which option may fit. No preparation is needed, and there is no obligation.
Step 2
Proposal and agreement
This is where you choose an ongoing relationship or project planning. I put the scope, deliverables, and fees in writing before discovery begins. You commit when you sign, and nothing is charged before then.
Step 3
Discovery
I gather your documents, clarify your financial details, and explore your goals in more depth, so I understand what your retirement needs to support.
Step 4
Analysis and recommendations
I analyze the questions covered by your engagement, including how Medicare premium (IRMAA) effects fit alongside your income needs and taxes, and prepare written findings and recommendations. Together, we review the results, discuss your options, and prioritize your next steps.
Step 5
Implementation and continued support
Ongoing clients receive help putting the strategies in place, investment management, and regular reviews as life changes. Project clients carry out the recommendations themselves.
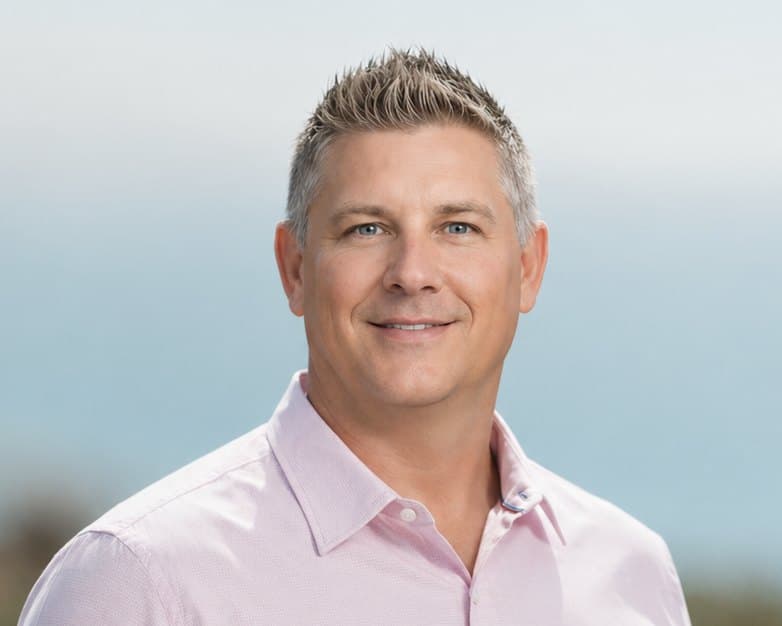
MEET PATRICK
Work Directly With Patrick
When you work with Sentient Financial, you work directly with me. I’m Patrick Thompson, Accredited Wealth Management Advisor™ and founder of Sentient Financial. I help people approaching retirement coordinate their investments, income and taxes so the pieces work together, rather than making each decision in isolation.
For more than 18 years, I’ve helped clients navigate the transition from building wealth to living from it. As a fee-only fiduciary, my role is straightforward: help you understand your options, make thoughtful decisions, and build a retirement strategy around your life, not a product.
Based in Laguna Niguel, I work with clients throughout South Orange County and virtually across the country.
A Little About Me
Outside of work, I’m a husband of 25 years and a father of two. I spend my free time hiking, fishing, mountain biking, golfing, and getting outdoors whenever I can. And I’ve been a Kansas City Chiefs fan since I was 13, which has been considerably more enjoyable in recent years.

Preparing for Retirement?
Watch the Retirement Transition Series
If you’re within 5–10 years of retirement, this series shows how to turn your savings into a reliable, tax-efficient retirement paycheck. Each episode walks through the key decisions (from income and taxes to Social Security and investment strategy) so you can approach retirement with clarity and confidence.
Fee-Only Advice. A Fiduciary Commitment to Your Best Interests.
I am paid by my clients and do not receive commissions from investment or insurance product sales. I disclose material conflicts and explain how I address them.
No commissions from product sales
No proprietary products
Material conflicts disclosed and explained

Understand the Decisions Ahead of Retirement
Start Here.
Download the free Retirement Transition Field Guide, written for professionals 5–10 years from retirement who want a clearer view of the decisions ahead.
It’s a practical way to organize your thinking before making any major moves.
Lower tax brackets are a use-it-or-lose-it opportunity each year, which is why timing matters.
Frequently Asked Questions
Read the FAQI am a good fit for individuals, couples, and business owners who value a long-term partnership with a fiduciary advisor and want a coordinated plan for retirement, investments, and taxes. Many of my clients are professionals and pre-retirees virtually across the nation and in person in South Orange County, including people within 5–10 years of retirement, equity‑compensated employees, and small business owners who want to organize a complex financial picture into an actionable plan. If you are looking for an advisor who is fee-only, transparent, and proactively involved in your financial life, not a salesperson, I may be a good fit.
Being a fiduciary means I am held to a standard of acting in your best interest when I give advice. I am paid by my clients and do not receive commissions from investment or insurance product sales. I disclose material conflicts and explain how I address them. Recommendations are based on your goals, risk tolerance, and long-term plan.
I offer two engagement options. Planning-only clients pay a one-time project fee, estimated in advance at $300 per hour and billed in 15-minute increments, with no ongoing asset-based fee and no asset minimum. Ongoing wealth management clients pay an annual advisory fee based on assets under management (AUM), which includes portfolio management, retirement planning, tax planning, and ongoing guidance. See how I work with clients, including fees and when payment begins.
The first step is a Fit Call. There’s no pressure and no sales pitch. I’ll discuss your goals, what’s working, what isn’t, and whether it makes sense to move forward together.
If you’re getting close to retirement and want to understand how this applies to your situation, that’s where our conversation starts.